Paid Media and Advertising
PPC Account Audit and Optimization Strategy
Independent PPC account audit diagnosing wasted spend, broken tracking, and bidding problems, delivered as a prioritized optimization roadmap.
Explore the detailWe run policy-safe Google, Meta, and TikTok campaigns for Pakistani healthcare, finance, insurance, and education advertisers, with claim review, compliant creative, and disapproval and suspension recovery built into the service.
Paid Media and Advertising
We run policy-safe Google, Meta, and TikTok campaigns for Pakistani healthcare, finance, insurance, and education advertisers, with claim review, compliant creative, and disapproval and suspension recovery built into the service.
Review useful outcomes alongside spend. State conversion definitions and attribution limits before making budget decisions.
A closer look
The approach, practical steps and decisions behind the plan.
Advertising a clinic, a takaful or insurance product, a loan, or a degree programme on Google or Meta means operating under a rulebook most agencies have never actually read. Platforms apply restricted-category policies to healthcare, finance, insurance, and education offers that a clothing brand or a restaurant will never encounter, and sitting above those platform rules are Pakistani regulators with requirements of their own. When the two layers collide, the outcome is familiar to every regulated advertiser in Pakistan: disapproved ads, frozen accounts, and media spend going nowhere. WeProms Digital runs paid media for regulated advertisers with compliance designed in from the first claim to the final landing page, so the account stays live and the budget keeps working.
Regulated advertisers fail review for reasons that have nothing to do with budget or bidding skill. A headline promising guaranteed returns, a landing page that describes a treatment outcome the page cannot evidence, or an image implying a medical result can each trigger a rejection that generic PPC staff struggle to explain, because the rejection cites a vertical policy they have never opened.
The problem is getting worse for two reasons. First, platforms increasingly require advertiser verification, category-specific certifications, and market-specific disclosures before regulated ads can serve at all, and those requirements change without much warning. Second, automation has entered the compliance path. Performance Max and similar formats assemble headlines, descriptions, and images from your site and feed, and those machine-generated combinations are still fully subject to ad policy. An account owner who never wrote “permanent relief” can still be disapproved for it, because the platform generated the phrase from an unreviewed product page. Automated asset generation does not transfer responsibility away from the advertiser, so the inputs, not just the ads, need reviewing.
There is also a copy trap that catches even careful teams. Platforms prohibit ads that state or imply personal attributes, which means copy like “Are you struggling with debt?” or “Do you have diabetes?” violates policy no matter how well it converts. Regulated industries are precisely the industries where empathetic, condition-aware copy feels most natural, which is why they are disproportionately disapproved for it.
We start by mapping what actually governs each offer. Which platform policies apply, whether the category requires certification or prior authorisation, what disclosures must appear, and which local regulations constrain the claims. This is done offer by offer, because a health insurance product and an Islamic financing product in the same ad account sit under different rules, and treating the account as one uniform thing is how violations slip through.
Every claim then passes through a review workflow before launch. Headlines, descriptions, image concepts, and the landing page statements they point to are screened against the mapped policies, so the promise in the ad is matched by evidence on the page. Ad-to-landing-page consistency is one of the most common silent disapproval triggers in finance and healthcare, and it is entirely preventable. Where a claim needs substantiation, we document what supports it, so that when a reviewer or an appeal process asks, the answer already exists instead of being assembled overnight under pressure.
The output is a campaign structure where compliance and performance point the same direction. Compliant copy is not weak copy; specific, substantiated claims tend to attract better-informed leads who convert at realistic expectations rather than arriving on inflated promises that the sales team then has to walk back.
Restricted categories face real limits on targeting. Credit-related products on Meta must run under a Special Ad Category that narrows age, location, and interest targeting, and sensitive health and financial categories restrict personalised advertising options elsewhere too. Agencies that ignore these settings get the account flagged; agencies that treat them as the end of the road quietly starve the campaign.
We do neither. The restrictions are configured correctly from day one, and the targeting depth that is no longer available through platform levers is rebuilt through first-party data, clearer offer positioning, and content that qualifies leads before they click. In practice, a well-structured compliant campaign with a precise offer outperforms a hyper-targeted campaign that gets suspended in week three.
When a disapproval lands, speed and precision matter. We triage which policy was cited, decide whether to fix the asset, replace it, or appeal, and act the same day, because a disapproved ad is not a nuisance, it is spend that is not delivering. Appeals are written from the policy text, citing the evidence pack assembled during claim review, which is why they succeed far more often than template appeals.
Account suspension is the serious case. A suspended account freezes every campaign at once, and the appeal window is where most advertisers lose months. We assess the violation, assemble the documentation the platform asks for, and run the appeal properly. We are also honest about odds: an account with repeated violations may be beyond recovery, and in those cases we say so and plan a clean rebuild rather than billing for appeals that will fail. Prevention is the other half of this work, because the cheapest suspension is the one that never happens, and that is what the daily policy monitoring and the pre-launch checklist exist for.
Platform policy is only the first layer for Pakistani advertisers. Therapeutic goods advertising falls under DRAP’s approval regime, where claims must match what was registered and direct-to-consumer advertising of certain products requires prior approval. Insurance and securities advertising carries SECP accuracy and disclosure requirements, including licensing details and fairness standards that apply to the advertisement itself, not just the product. Education advertisers face scrutiny over degree recognition and accreditation claims, where the safest ground is always what a recognised body actually accredits.
We check claims against both layers, and we check them in Urdu as well as English. A large share of the Pakistani audience converts on Urdu creative, and a risky claim does not become safe because it changed languages. Our ethical positioning also draws a hard line: we do not run gambling, alcohol, riba-based, or adult advertising, and we keep that line even where platforms might technically permit an offer.
This service is for regulated advertisers in Pakistan who cannot afford dead spend or a suspended account: hospitals, clinics, and telehealth platforms; Shariah-compliant banks, insurers, takaful operators, and lenders; universities, degree programmes, and study-abroad consultancies; and internal marketing teams at larger organisations that need a partner who reads policy as fluently as they read performance dashboards. If your offers sit under rules other advertisers never face, this is the service built for that reality.
Related services
Paid Media and Advertising
Independent PPC account audit diagnosing wasted spend, broken tracking, and bidding problems, delivered as a prioritized optimization roadmap.
Explore the detailPaid Media and Advertising
Manage Google Ads with better structure, intent targeting, and conversion performance.
Explore the detailPaid Media and Advertising
Scale Facebook and Instagram ads with stronger creative testing and audience strategy.
Explore the detailA few of the brands we’ve worked with.

See where the work happens and get to know WeProms before your first conversation. Our team is based in Lahore, working with business owners abroad and at home.
Get to know WeProms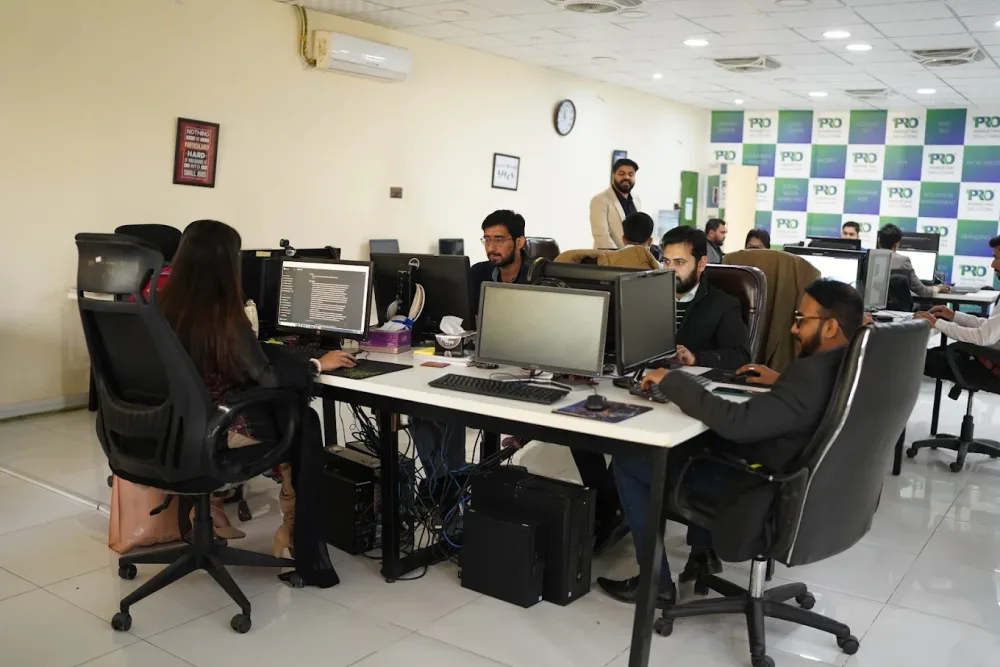 Watch our introduction
Published client experiences
Hear what working with WeProms was like, directly from our clients.
 Watch their story
Their business journey
 Watch their story
Client feedback
 Watch their story
Working with WeProms
Inside WeProms
Lahore, Pakistan
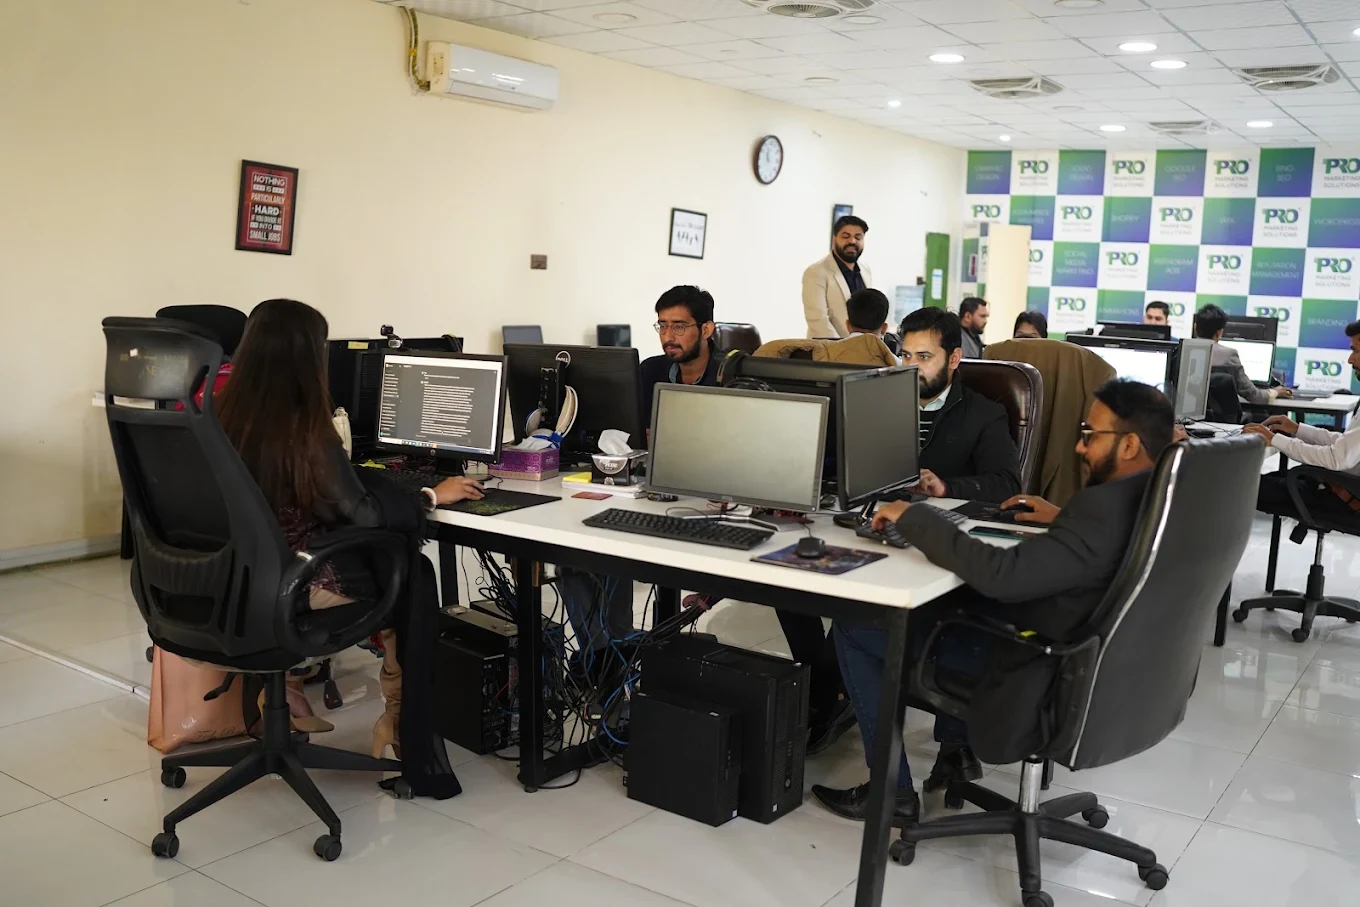
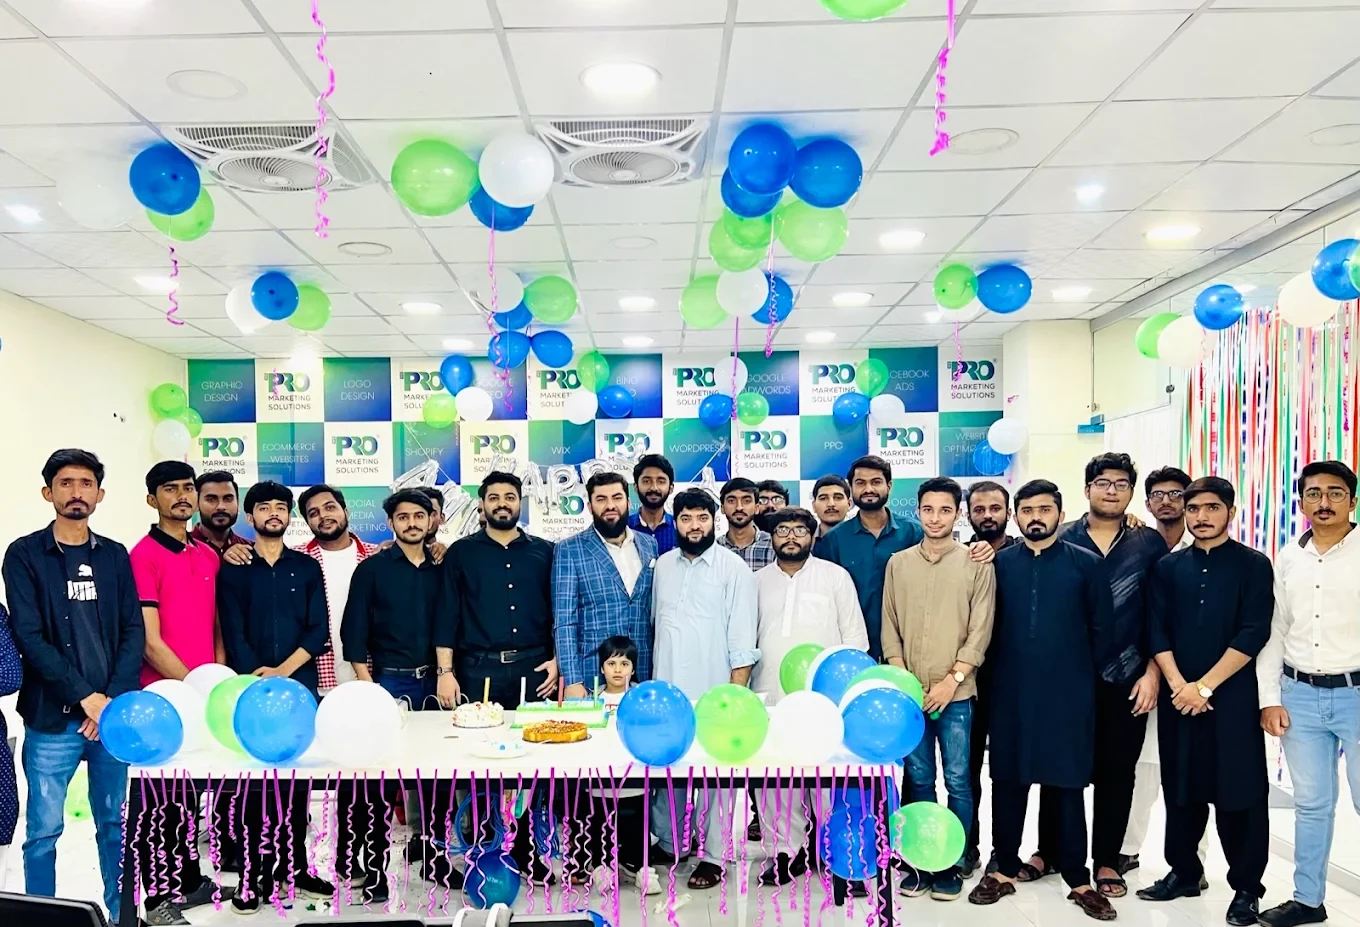
154, C1, Nespak Housing Scheme, Lahore 54770, Pakistan.
Working with a remote marketing team
You know your customers and market. Our strategists, creatives and technical specialists in Lahore help put the plan into practice. Agree the contact person, meeting times and approvals before we start.
Agree deliverables and the agency fee. Discuss ad spend and third-party tools separately.
Keep visibility and ownership. Agree access, asset licences and handover as part of the scope.
Agree a review schedule around your time zone. See what was delivered, what the numbers mean and what comes next.
Explore our Pakistan pricing guides for planning ranges and what shapes the cost. Your market, deliverables and existing setup determine the final quote; advertising spend and third-party costs are separate.
Discuss a quote for your market ↗Before the next step
A useful starting brief includes: account and spend history; approved offers and creative; lead-quality or order feedback. We can agree appropriate access after the first conversation.
Review useful outcomes alongside spend. State conversion definitions and attribution limits before making budget decisions.
We can discuss a one-off implementation, an ongoing scope or an initial build followed by support. The proposal states what is included, dependencies and the review points.
Agency work, media spend and third-party costs are identified separately. Your market, existing setup and delivery requirements determine the final scope and quote.
Share your website, target country and the next thing you want to improve. We’ll help you find a useful place to start.